ServicesBox Truck Insurance
Box Truck Insurance in Alpharetta
We build box truck policies around the work you actually run: final-mile freight, load board runs, furniture or contract routes. One person quotes your coverage, sends your filings and issues your certificates, so you always know who to ask.
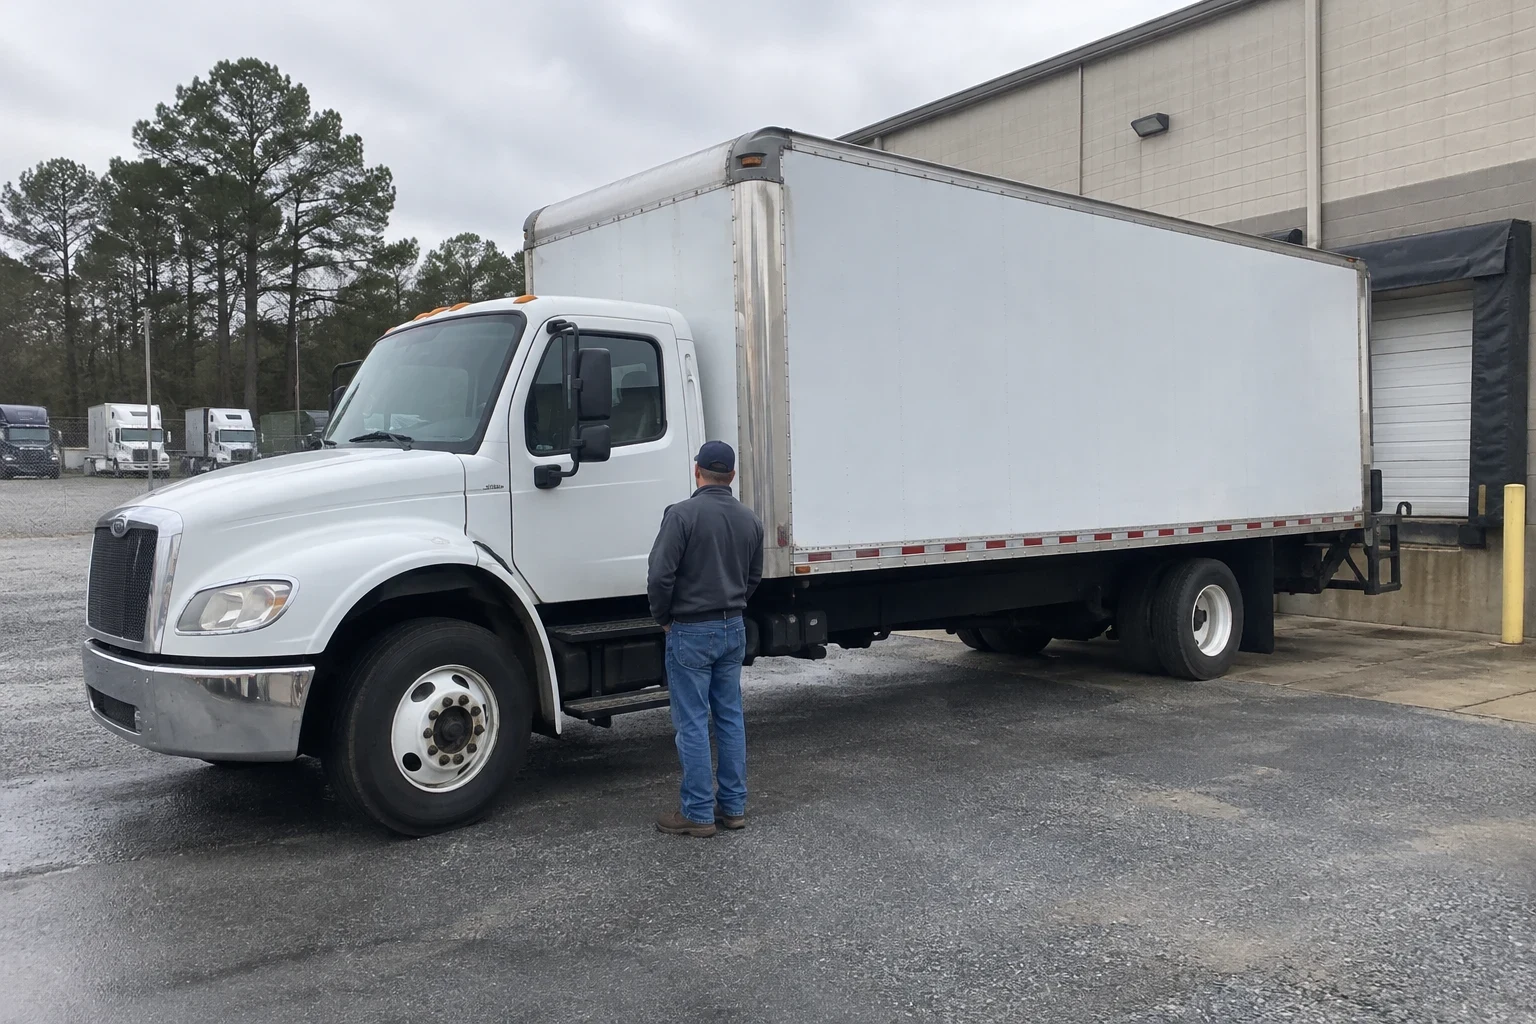
What box truck insurance covers and who needs it
A box truck sits in an odd spot. Most are under 26,001 pounds GVWR, so no CDL is needed, but once your truck is over 10,001 pounds and hauls for hire across state lines, you need a DOT number, MC authority and liability filed with the FMCSA. Many operators find out the hard way that a commercial auto policy written for a contractor's van does not satisfy a broker or a shipper.
Box truck insurance is usually a package: primary auto liability, motor truck cargo, physical damage on the truck and liftgate, and often general liability for the time you spend on a customer's dock. We work out which pieces your contracts require and which are worth having. Then the same person stays on your file, so a broker's certificate request or a mid-term truck swap goes to someone who already knows your operation.
What we put together for your box truck
- Primary auto liability and filings
- This pays for injury and damage you cause to others on the road. We file proof with the FMCSA under your DOT number so your authority stays active, and with the state where it applies.
- Cargo coverage that matches your freight
- We read the cargo form for exclusions that catch box truck operators: unattended vehicle theft, electronics, refrigeration breakdown and loads left in the truck overnight. If you haul furniture and appliances for a moving company, the limit and form have to fit that freight.
- Physical damage on the truck and equipment
- Comprehensive and collision on the cab, the box and add-ons like a liftgate or reefer unit. If the truck is financed, we set the lienholder up correctly so the lender stops sending letters.
- General liability for dock and delivery work
- Backing into a loading door or scuffing a customer's floor during a delivery is not always an auto claim. General liability fills that gap, and many final-mile contracts ask for it by name.
- Certificates of insurance on request
- Brokers, shippers and warehouses want a certificate naming them before you load. You call one person, give the holder's details, and we issue it.
Signs your box truck coverage needs a closer look
A broker rejected your certificate
Usually the cargo limit is too low, the liability is not on file with the FMCSA, or the policy lists the wrong radius. Each one has a specific fix.
You moved from local to interstate runs
Crossing into Tennessee or Alabama for a load changes your filing requirements. A policy written for intrastate work may not cover you.
Your truck is listed as a light commercial vehicle
If a personal or small business auto policy covers a 26-foot box truck hauling for hire, a claim could be denied over how the truck is actually used.
You added a liftgate or reefer
Equipment bolted on after the policy started may not be included in the stated value. We update the schedule so a loss pays on what is really on the truck.
You signed a contract with new insurance terms
Final-mile and dedicated route agreements often require specific limits, wording that names the shipper on your policy, or a waiver of subrogation. We check the contract language against your policy before you sign.
How a box truck quote works with us
- 1
A phone call about your operation
We ask about your truck's GVWR, length, what you haul, how far you run and who your drivers are. Having your DOT number and VIN handy speeds things up.
- 2
We shop the market
Box truck risks get priced very differently from one insurer to the next. We take your details to carriers that write straight trucks and compare the forms, not just the premium.
- 3
We walk you through the options
You hear what each quote covers, what it excludes and where the deductibles sit. If a cheaper option has a cargo exclusion that matters for your freight, we tell you.
- 4
Binding, filings and certificates
Once you choose on the call, we bind coverage, put your filings on record with the FMCSA and issue the certificates your brokers need. The same person handles changes, renewals and claim questions afterward.
What moves your box truck premium
Box truck premiums swing widely because insurers price the driver, the freight and the miles as much as the truck. We can't quote a number without your details, but these are the factors that matter most. Knowing them helps you see why two quotes can look so different.
- Driver history and experience
- Violations, at-fault accidents and fewer than two years of commercial driving push rates up. Every listed driver is rated, not just the owner.
- Radius and type of work
- Local final-mile routes rate differently than long-haul load board work. Freight type matters too, since electronics and furniture moving loads carry more cargo risk than boxed dry goods.
- Authority age and loss history
- New MC authority usually pays more until it builds a clean record. Our New Authority Truck Insurance page explains that first year in detail.
- Truck value and equipment
- Stated value, liftgates and reefer units all affect physical damage premium. Higher deductibles lower it, but you carry more on each claim.
- Limits and endorsements
- Higher liability or cargo limits, naming customers on the policy and general liability all add cost. We match them to what your contracts actually require.
Box truck insurance questions
Something not covered here? (770) 270-3686
Do I need a DOT number for my box truck?
If your truck has a GVWR over 10,001 pounds and you haul for hire across state lines, yes. Interstate for-hire work also usually requires MC authority. We can explain which applies to your routes before we quote.
Does my box truck need a CDL driver?
Most box trucks are rated at or under 26,000 pounds GVWR, so no CDL is needed. Insurers still look closely at non-CDL drivers' records and experience, and that affects your premium.
Will my policy work for Amazon Relay or final-mile contracts?
It can, as long as the limits, cargo form and the wording that names the shipper or broker on your policy match the contract. Have the insurance requirements in front of you when you call, and we will go through them line by line before binding.
Is cargo theft from an unattended truck covered?
Many cargo forms exclude or limit theft when the truck is left unattended or unlocked. We point out that wording and look for forms that fit how you park and stage freight.
Can I add a second box truck mid-term?
Yes. Call the person handling your policy with the VIN, value and driver, and we will add it and update your filings and certificates. Once you run several trucks, our Fleet Truck Insurance page explains how a fleet policy can be set up.
Talk through your box truck coverage
Have your DOT number, VIN and driver list ready, and we will go over what your work needs. You will hear back from the same person who quotes you.