ServicesDump Truck Insurance
Dump Truck and Construction Truck Insurance in Alpharetta
Dump trucks are rated differently from over-the-road freight: short radius, heavy loads, raised beds and jobsite contracts that demand specific certificate wording. We build coverage around how your trucks actually work, and one person handles your quote, filings and certificates.
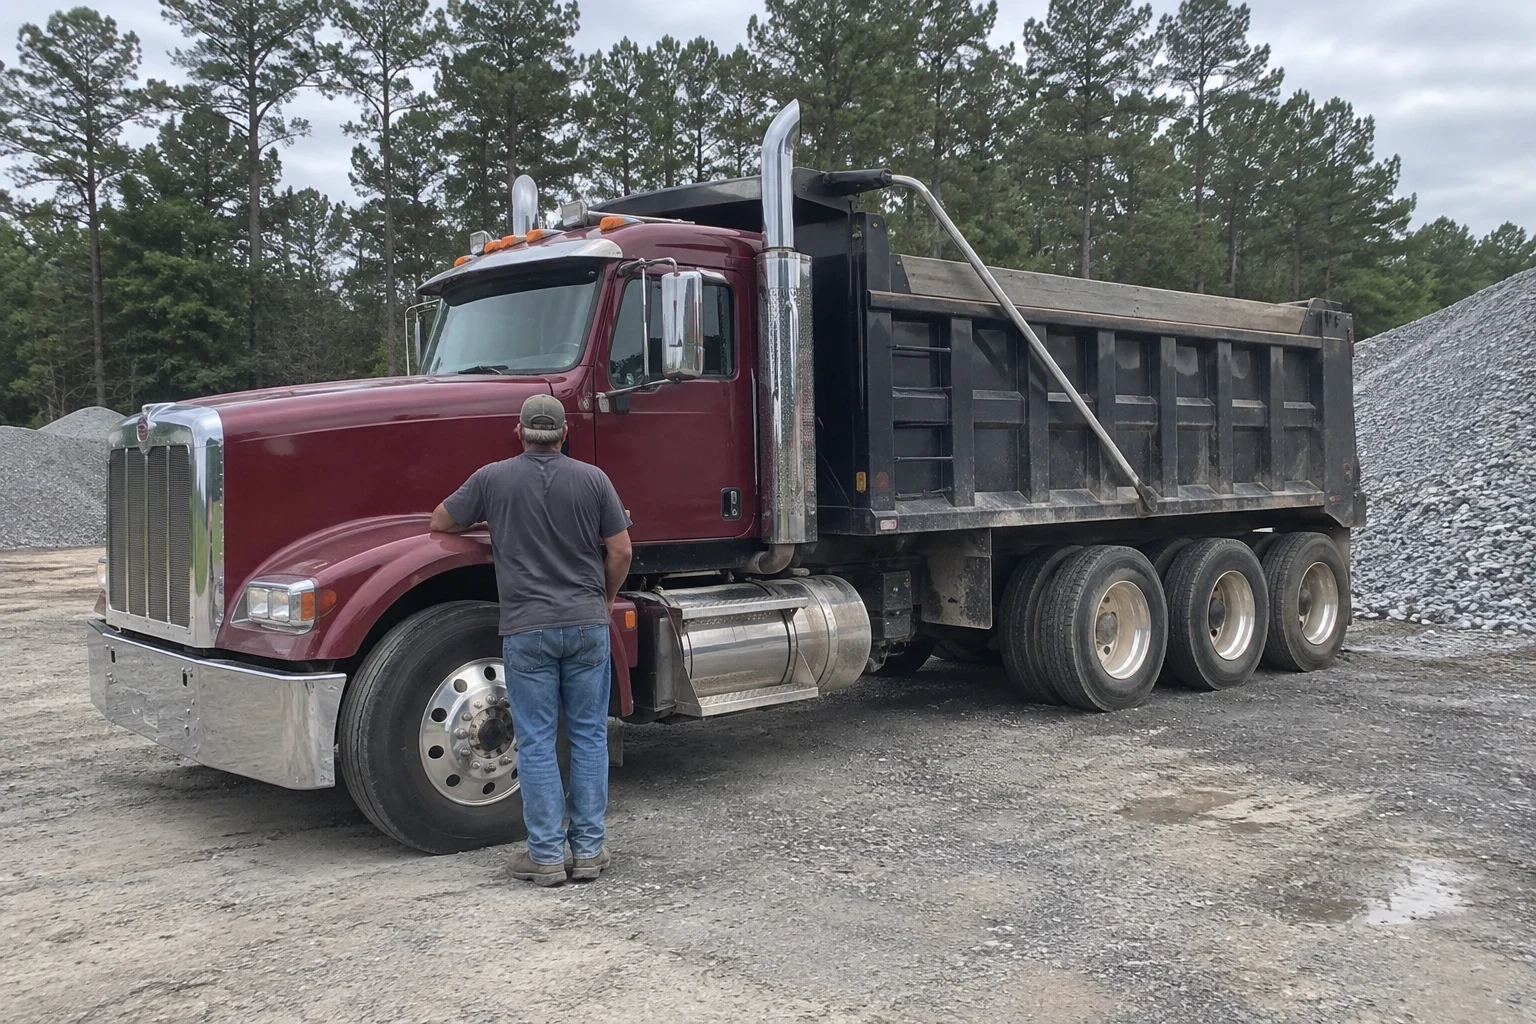
Coverage built for haul jobs, not freight lanes
A tri-axle hauling crushed stone forty miles a day carries a different risk than a sleeper tractor running interstate freight. Underwriters look at your radius of operation, what you haul, the value of the truck and dump body, and who drives. Get those details wrong on the application and you can end up with a policy that excludes the work you do every day.
We write dump truck and construction truck insurance for owner-operators and small fleets running tandems, tri-axles, quad-axles, end dumps, side dumps, roll-offs and mixers. Most clients work jobs around Alpharetta, Roswell, Woodstock and the rest of the north metro.
You deal with one person from the first call. That person learns your operation, shops the coverage, files what needs filing and sends certificates when a general contractor asks for them.
What a dump truck policy usually includes
- Primary auto liability
- This pays for injury and property damage you cause to others while operating. Many site contracts and public projects require a set limit, so we match your limit to the contracts you bid. See our Primary Auto Liability Insurance page for how limits are set.
- Physical damage for truck and dump body
- Comprehensive and collision for the chassis, plus the dump body, hoist and PTO when they are scheduled at their real value. A body added after purchase is easy to leave off the stated value, and that gap shows up only at claim time.
- Upset and overturn
- A raised bed on soft or uneven ground can tip the whole truck. Some policies limit or exclude damage from an overturn while dumping. We check for that wording and explain what it means before you sign.
- Cargo, when it applies
- Sand, gravel and fill often need little or no cargo coverage, but hauling for hire on equipment or materials you do not own can. We sort out whether Motor Truck Cargo Insurance belongs on your policy.
- Certificates and filings
- Certificates of insurance with the endorsements contractors ask for, such as naming their company on your policy and waiver of subrogation, plus the state or federal filings tied to your DOT number.
Signs your current coverage does not fit the work
A contractor rejected your certificate
General contractors often require their company to be named on your policy with primary and noncontributory wording. If your certificate came back, the policy may need an endorsement, not just a new form.
Your jobs moved farther out
Dump policies are often rated on a radius. If you used to stay within fifty miles and now take jobs well beyond that, the declared radius may no longer match.
You added a truck or a driver
Every unit and driver has to be scheduled. An unlisted driver with a rough MVR can create a coverage dispute after an accident.
The dump body is not listed separately
If the declarations show only the chassis value, a total loss could pay far less than it costs to replace the truck and body together.
Renewal jumped and nobody explained why
Premium moves for reasons: a claim, a driver violation, a change in carrier appetite. You should know which one it was.
How we set up your policy
- 1
A detailed first call
We ask what you haul, typical radius, truck year and make, body type and value, drivers and any loss history. Ten specific minutes here prevent most mid-term surprises.
- 2
Shopping the market
We take your file to carriers that write dump and construction risks and compare the exclusions as well as the premium. Two quotes at the same price can treat an overturn very differently.
- 3
Walking through the options
By phone or video, or at our office, we go line by line through limits, deductibles and endorsements. You choose with the tradeoffs laid out plainly.
- 4
Binding, filings and certificates
Once bound, we handle required filings and issue certificates to your contractors. When a new job needs one, you call the same person who set up the policy.
What moves the premium on a dump truck
No two dump operations price the same, because carriers rate the specific risk. These are the factors that move a quote the most. We can show you which ones are pushing yours.
- Radius and type of hauling
- Local aggregate runs usually rate differently from long-distance hauls. Demolition debris and asphalt can price differently than clean fill.
- Truck and body value
- Physical damage premium follows the stated value of the chassis, body and hoist. Newer equipment costs more to insure for damage.
- Drivers
- Age, years of commercial driving experience and MVR history weigh heavily. One serious violation can shift the whole policy.
- Loss history and limits
- Prior claims and the liability limit your contracts demand both move the price. Higher deductibles can offset some of it.
Dump truck insurance questions
Something not covered here? (770) 270-3686
Does physical damage cover my dump body and hoist?
It can, if they are included in the stated value on the policy. Many owners list only the chassis price. We confirm the body, hoist and PTO are scheduled so a total loss reflects the whole unit.
Do I need cargo coverage hauling dirt and gravel?
Often not, since the material has little value and may belong to you. If you haul for hire on equipment, pipe or other valuable materials, cargo coverage becomes worth discussing. We look at your actual loads before recommending it.
Can you name a general contractor on my policy so their certificate is accepted?
Yes, when the carrier allows the endorsement, and most dump truck carriers do. Read us the contract requirements over the phone or bring the contract to our office. We check the policy wording against each requirement before issuing the certificate, so it is not sent back.
What happens if my truck tips while dumping?
That depends on whether the policy limits or excludes upset and overturn while the bed is raised. Collision coverage typically responds, but some forms carve this out. We point to the exact wording in your quote so you know before a loss.
I run one truck now but plan to add more. Should I set up differently?
Tell us your growth plan on the first call. Some carriers handle a move from one truck to three easily, while others re-underwrite. Our Fleet Truck Insurance page covers what changes as you add units.
Get dump truck coverage that matches your jobs
Have your truck details, body value and driver list handy. One call starts the quote, and the same person stays on your file after it is bound.